Responsible Money
Buy Now, Pay Later During Holiday Sales: When It Helps and When It Hurts Filipino Shoppers

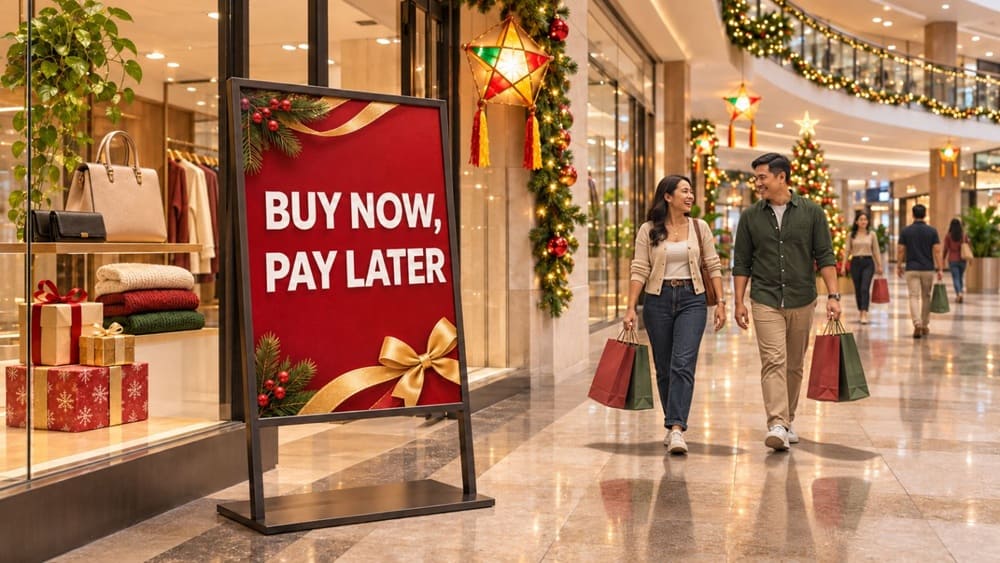
Buy now, pay later (BNPL) can make Christmas shopping feel lighter by splitting a purchase into installments, but it can also turn a “sale” into a January debt problem. For Filipino shoppers, the safest rule is simple: use BNPL only for something you already planned and can fully pay from your expected income or 13th-month pay.
How BNPL works
BNPL lets you buy now through apps or online stores, such as GCash GGives, Atome, BillEase, SPayLater, or Lazada PayLater, and repay in installments. Some standard short-term plans advertise 0% interest, while longer terms may charge monthly interest, processing fees, or late-payment charges.
For example, Atome’s standard three-installment split may be 0% interest, but a missed payment can incur a one-time administration fee of about ₱300. GCash GGives may charge 1% of the loan amount for each missed due date, plus a daily charge on the outstanding principal.
When it can help
BNPL is most useful when it helps you manage timing, not when it lets you buy something you cannot afford.
You already budgeted for the item. If a ₱4,000 appliance or gift is in your Christmas budget, splitting it into smaller payments can help you avoid draining cash needed for food, utilities, or transportation.
The plan is truly 0% and you can pay on time. A no-interest installment can be cheaper than carrying a credit-card balance, provided you understand the full schedule.
You are buying a practical need. School supplies, a replacement phone, home repairs, or a necessary appliance may be more sensible BNPL uses than impulse “add to cart” purchases.
You use your 13th-month pay wisely. Financial guides recommend allocating 13th-month pay first to bills, savings, and existing debt, then setting aside only a planned amount for Christmas spending.
When it hurts
The biggest risk is that BNPL makes a large amount feel small. A ₱6,000 phone becomes “only ₱2,000 today,” but you still owe the remaining ₱4,000, often just when January bills, tuition, and everyday expenses arrive.
It can encourage overspending during 9.9, 10.10, 11.11, and Christmas sales. Easy installments can make shoppers buy more than their budget allows.
Multiple plans can pile up. Having several BNPL loans across GCash, Shopee, Lazada, and online stores can create several due dates in one month.
Late fees and interest can erase the discount. Some BNPL products charge late fees, daily penalties, or monthly interest; one provider’s late charge can reach 5% of the outstanding principal per month.
It can affect future borrowing. BNPL is real credit, not “free” money. Missed payments can affect your standing with the provider and, depending on the platform, your future credit eligibility or limit.
It can eat your 13th-month pay. If you spend the bonus before it arrives and use BNPL to cover the gap, you may enter the new year still paying for last year’s holidays.
A Filipino holiday checklist
Before tapping “Pay Later,” ask yourself:
- Can I afford to pay the full amount right now? If not, the purchase may be too expensive for your current budget.
- Will I have money on the exact due date? Check your salary, 13th-month pay schedule, remittances, and regular bills.
- How many BNPL plans do I currently have? Keep it to one active plan if possible; avoid stacking loans across apps.
- What is the total amount I will pay? Include interest, service fees, delivery fees, and possible late charges, not just the monthly installment.
- Are the due dates on my calendar? Set reminders a few days before each payment.
- Do I have an emergency fund? Do not commit money needed for rent, food, medicine, utilities, or family emergencies.
Smarter alternatives
- Save small amounts early in the Ber months. Setting aside money before December reduces the temptation to rely on installments.
- Use cash or debit for impulse purchases. If you cannot pay in full, wait for the next payday or sale.
- Prioritize high-interest debt. If you already have BNPL or credit-card balances, financial guidance suggests paying those before adding new holiday spending.
- Set a gift list and price limit. Decide who you are buying for and how much you will spend before browsing sales.
- Use BNPL for one planned purchase only. Treat it as a budgeting tool, not extra shopping money.
BNPL can help Filipino shoppers during holiday sales when it spreads the cost of a planned, affordable purchase without interest or fees. It hurts when it fuels impulse buying, stacks multiple debts, or leaves you paying for Noche Buena and gifts well into January. The best holiday deal is still one that fits your budget, without turning your 13th-month pay into a repayment plan.


You must be logged in to post a comment Login