Responsible Money
Separating Business Savings from Personal Savings Accounts: A Practical Guide for Small-Business Owners

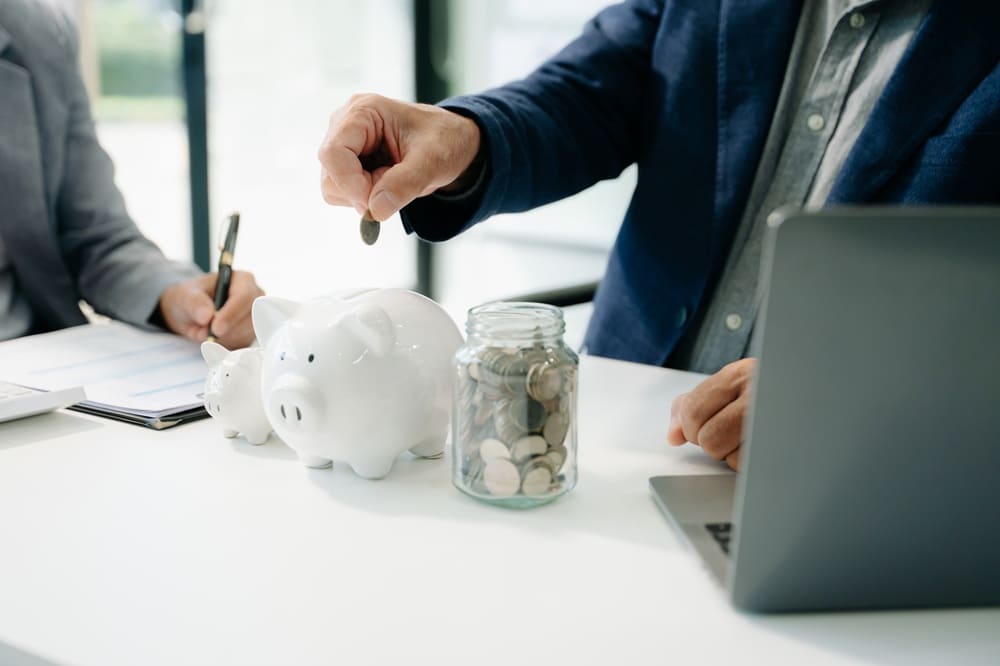
Keeping business savings separate from personal savings is one of the simplest yet most powerful financial habits a small-business owner can build. It protects your personal assets, simplifies taxes, and gives you a clear view of your business’s true financial health.
Why Separation Matters
Mixing business and personal funds, often called “commingling”, creates avoidable risks and headaches.
Legal protection: If your business is a corporation, separate accounts help maintain the “corporate veil.” This makes it harder for creditors or plaintiffs to reach your personal home, savings, or retirement accounts if something goes wrong with the business.
Cleaner taxes: Dedicated accounts make business income and expenses easier to track. This reduces the chance of missing deductions or misreporting income at tax time.
Accurate financial picture: Separate accounts let you see real profit numbers, cash flow, and how much you’ve saved specifically for business goals like taxes, equipment, or emergencies.
Professionalism and credit: Banks, lenders, and vendors take your business more seriously when it has its own accounts and transaction history, which can help you build business credit over time.
What’s Different About a Business Savings Account?
A business savings account works like a personal savings account but is structured for company use. It’s opened under your business name and TIN, not your personal name and personal TIN.
It’s meant to hold company funds for goals like tax reserves, emergency funds, or planned large expenses, not personal goals like vacations or household bills.
Income from a personal savings account is reported on your personal tax return, while business savings are part of your business records and financial statements.
Business accounts may have different transaction limits, fees, and documentation requirements than personal accounts.
Common Mistakes When Accounts Are Mixed
Many owners start by using one personal account for everything, then struggle later.
Typical problems include unclear profit. You can’t tell how much the business actually earns after expenses. Tax stress. Come tax season, you’re digging through personal statements to find business transactions, increasing the risk of errors or audits. Weakened liability shield. Courts may “pierce the corporate veil” if personal and business funds are heavily commingled, putting personal assets at risk. Cash-flow confusion. You might unknowingly use personal savings to cover business shortfalls (or vice versa), masking real cash-flow issues.
Step-by-Step: How to Separate Business and Personal Savings
You don’t need a complex setup to get started. Even sole proprietors can and should separate their finances.
1. Establish Your Business Identity (If Applicable)
If you have a corporation or partnership, ensure your business is registered.
2. Open Dedicated Business Bank Accounts
Aim for at least two business accounts:
- Business checking: For daily operations, receiving revenue, paying vendors, payroll, and routine expenses.
- Business savings: For funds you’re intentionally setting aside, such as tax reserves (many advisors suggest 25-30% of business income), Emergency fund (3-6 months of business expenses, if possible), planned large expenses (equipment, renovations, marketing campaigns).
3. Route All Business Money Through Business Accounts
Deposit all business income into your business checking account. Pay all business expenses from the business checking account, not your personal account. Transfer money from business checking to business savings on a regular schedule (e.g., monthly) to build your reserves systematically.
4. Pay Yourself Deliberately
Instead of dipping into business funds whenever you need cash, set a regular owner’s draw or salary. Transfer that amount from your business checking to your personal account on a set day (e.g., the 1st and 15th of each month). Use only your personal account for personal bills and lifestyle expenses.
Every transfer from business to personal should be labeled clearly in your books as “owner’s draw,” “owner distribution,” or “salary.”
5. Set Up Separate Bookkeeping
Use accounting software or a simple spreadsheet to track business income, expenses, and transfers. Reconcile your business checking and savings accounts monthly against your records. Keep all business receipts, invoices, and bank statements organized and separate from personal documents.
How Much Should You Keep in Business Savings?
There’s no one-size-fits-all number, but these guidelines help:
Tax reserve: Set aside 25-30% of net business income in a dedicated business savings account for quarterly or annual taxes.
Emergency fund: Aim for 3-6 months of essential business expenses if your income is variable or your industry is sensitive to economic shifts.
Planned expenses: Create separate “buckets” (even if mentally) for known upcoming costs like equipment upgrades, insurance premiums, or seasonal inventory purchases.
Your business savings account is the right home for these reserves because the money stays accessible but separate from daily spending.
What If You’ve Already Mixed Your Accounts?
It’s common to start out with everything in one account. You can clean things up.
- Open new business accounts (checking and savings) now.
- Review past personal statements and identify all business-related transactions.
- Categorize and document those transactions in your bookkeeping system.
- Move forward cleanly: From today on, route all new business income and expenses through your business accounts only.
- Talk to a tax professional if you’re unsure how to handle past commingling on your tax returns.
Simple Rules to Remember
To keep separation easy and sustainable:
One rule: No personal bills paid directly from business accounts.
One habit: Pay yourself on a schedule, not randomly.
One mindset: Treat your business as its own financial entity, even if it’s just you.


You must be logged in to post a comment Login